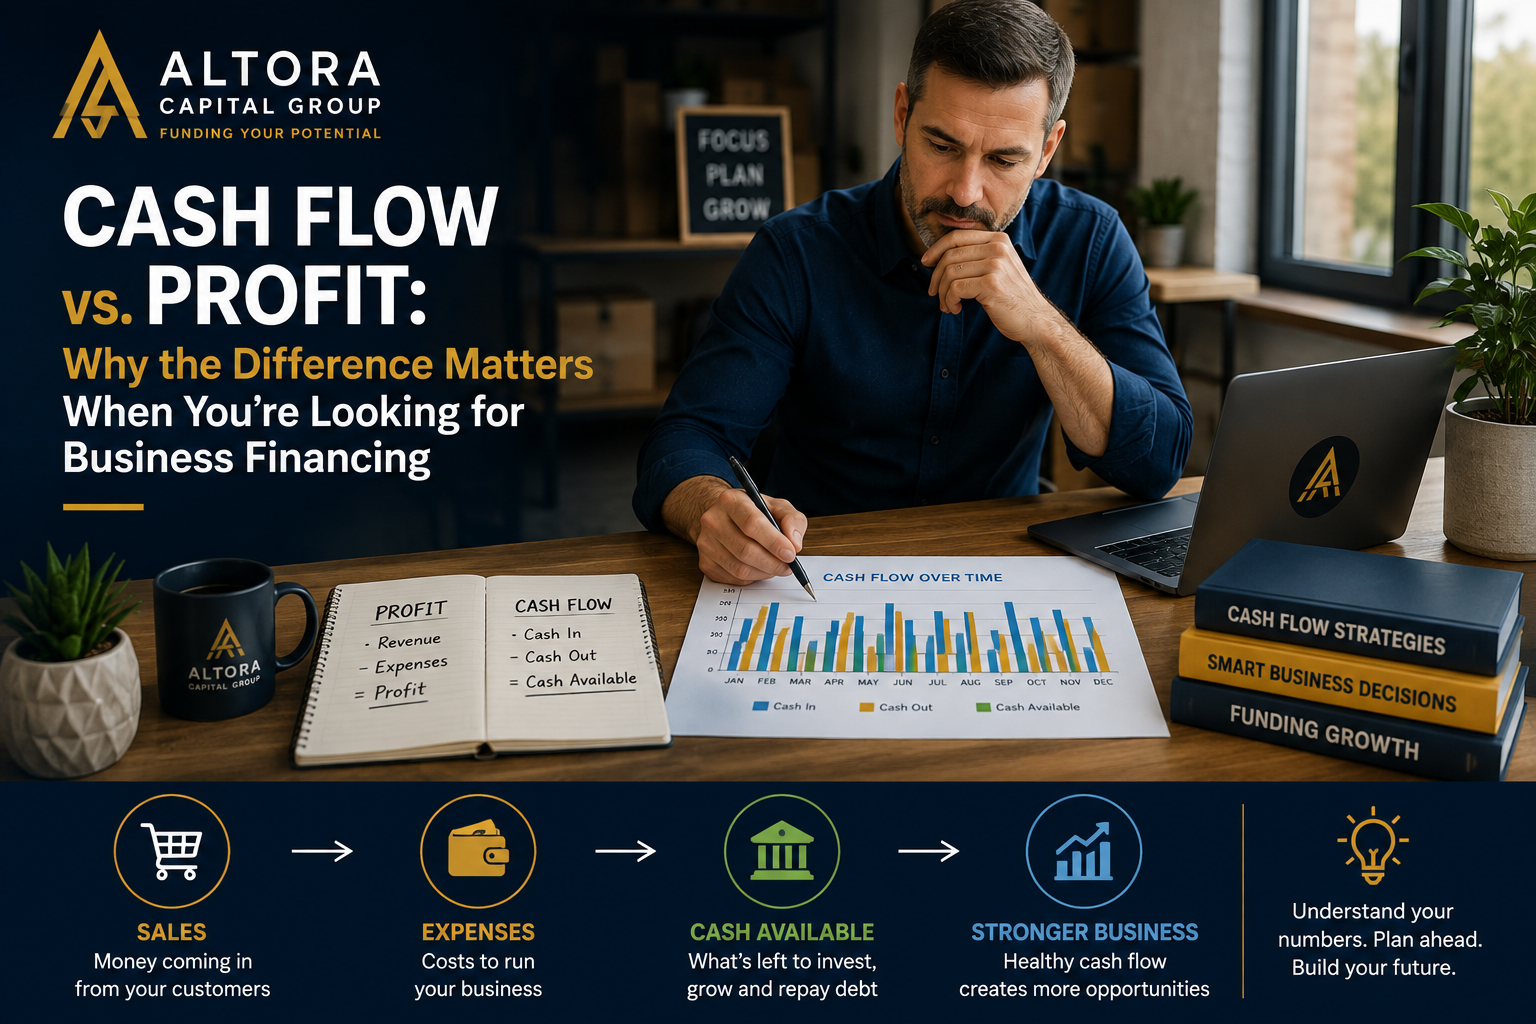
Cash Flow vs. Profit: Why the Difference Matters When You're Looking for Business Financing
Profit can look great on paper. Cash flow shows what is actually moving through your business.
Business owners often use the words profit and cash flow as if they mean the same thing. They do not.
A business can be profitable and still find itself short on cash. It can also have strong cash coming in during a busy period while its overall profitability remains weak. Understanding the difference can help you make better decisions about growth, expenses, and whether financing makes sense for your business.
Both can matter when you are evaluating how much additional financial obligation your business can realistically handle.
What Is Profit?
Profit is what remains after business expenses are subtracted from revenue over a specific period of time.
Revenue
The money your business earns from selling products or services.
Profit
What remains after the expenses associated with operating the business are deducted from revenue.
Profit helps show whether the business model is producing more income than expense over time. That is important, but it does not necessarily tell you how much cash is sitting in the business bank account today.
What Is Cash Flow?
Cash flow is the movement of money into and out of your business.
Cash comes in through customer payments, sales, receivables, financing, or other sources. Cash goes out for payroll, rent, inventory, equipment, taxes, loan payments, utilities, insurance, and other operating expenses.
Positive cash flow generally means more cash is coming into the business than going out during a given period. Negative cash flow means the opposite.
How Can a Profitable Business Run Short of Cash?
Imagine a business completes a large project and records the revenue, but the customer does not pay the invoice for 45 days. On paper, the project may be profitable. In the meantime, the business may still need to cover payroll, materials, rent, and other expenses before the customer payment arrives.
That timing difference is one of the reasons profitability and available cash can tell very different stories.
Common Things That Can Affect Cash Flow
Slow-paying customers
You may have earned the revenue but still be waiting for the actual cash.
Seasonality
Revenue may fluctuate significantly between busy and slower months.
Inventory purchases
Cash may leave the business before the inventory produces revenue.
Unexpected expenses
Repairs, equipment needs, taxes, or other costs can quickly change the cash position.
Why Cash Flow Matters When Considering Business Financing
When you take on financing, you are usually adding another recurring payment to the business. That means the important question is not simply, “Can I get approved?”
Looking at your recent cash flow can help you think through that question before you commit to additional financing.
Look Beyond One Good Month
A particularly strong month can make the business appear more comfortable than it normally is. When reviewing your cash position, look at several months rather than one isolated period.
Consider whether revenue is consistent, whether certain expenses occur only at specific times of year, and whether your business experiences predictable seasonal highs and lows.
Ways to Better Understand Your Cash Position
Review your business bank activity regularly. Know roughly what is coming in and what is going out.
Track accounts receivable. Money customers owe you is not the same as cash already available to spend.
Know your major recurring expenses. Payroll, rent, insurance, inventory, debt payments, and other obligations can significantly affect available cash.
Plan for slower periods. If your business is seasonal, prepare for the months when revenue normally declines.
Understand existing debt payments. Know what financial commitments the business already has before adding another one.
Profit and Cash Flow Work Together
Neither number should be viewed in isolation. Profitability can help show whether the business is financially sustainable over time, while cash flow helps show whether the business has enough money available to meet its obligations as they come due.
The Bottom Line
A profitable business can still experience cash shortages, and strong cash flow during one period does not automatically mean the business is consistently profitable.
Before pursuing business financing, take some time to understand both sides of the equation. Knowing your numbers can help you determine how much financing may make sense, what type of payment your business can comfortably handle, and whether now is the right time to move forward.
Not Sure How Financing Would Fit Into Your Cash Flow?
Sometimes it is easier to talk it through. Tell us about your business, what you are trying to accomplish, and what your current situation looks like.
This article is for general informational purposes only and is not accounting, tax, legal, or financial advice. Financing options, approval amounts, rates, terms, and eligibility requirements vary by provider and are subject to individual review and approval.