 ALTORA
CAPITAL GROUP
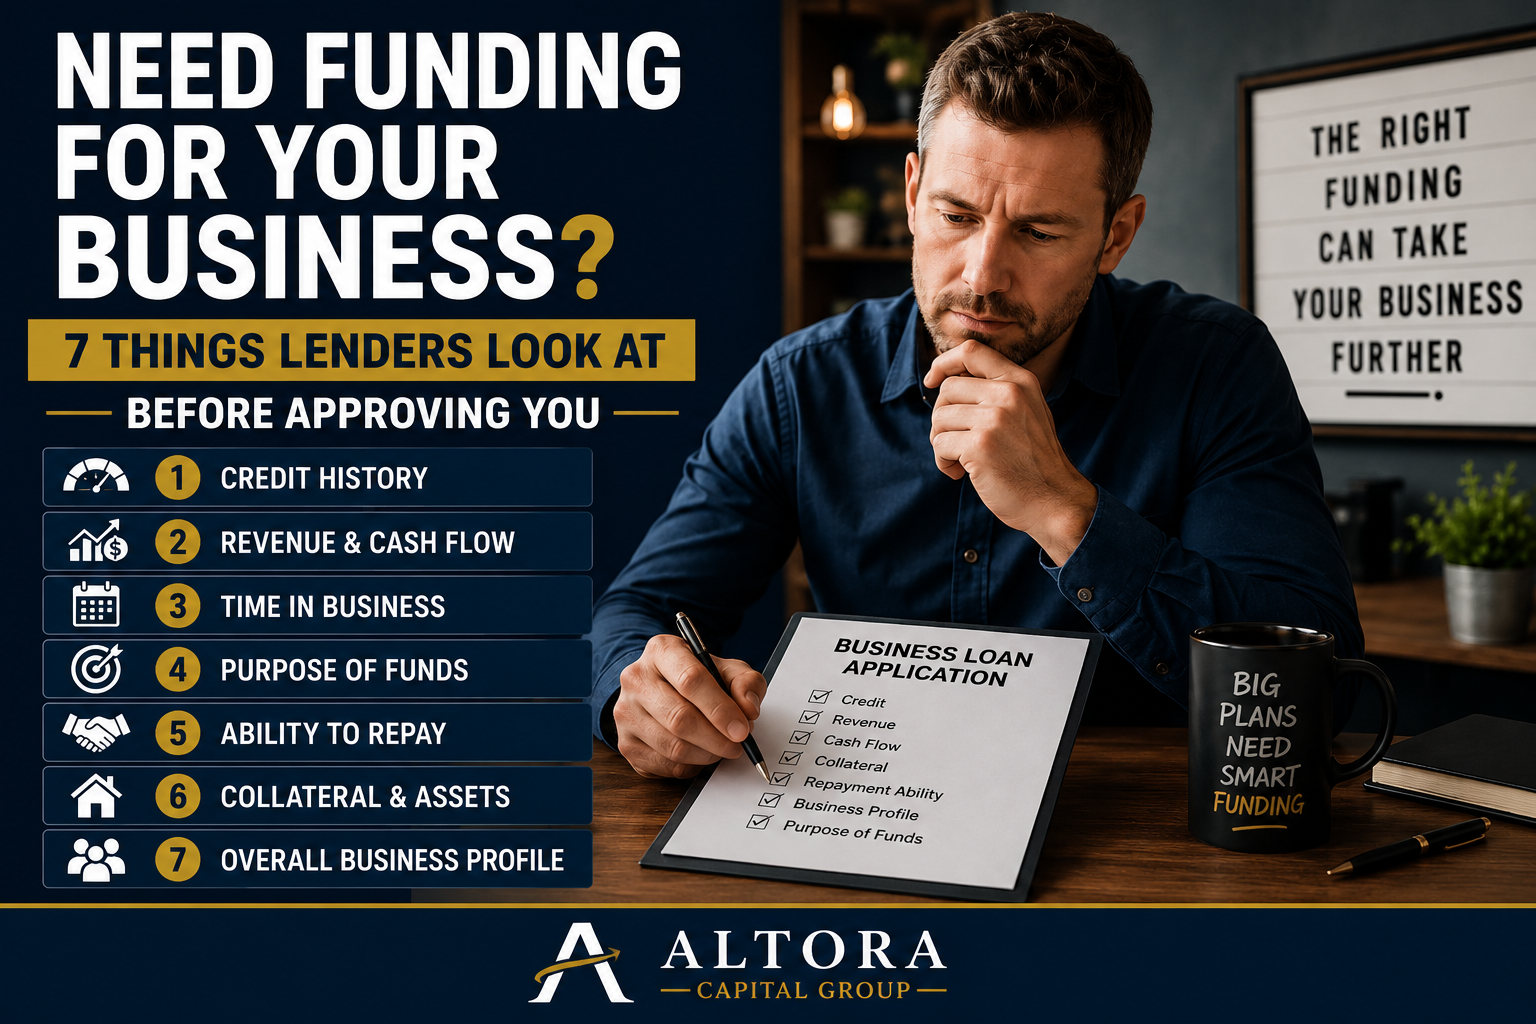
Need Funding for Your Business? 7 Things Lenders Look At Before Approving You
Whether you're purchasing equipment, hiring employees, expanding, managing cash flow, buying inventory, or preparing for your next opportunity, the right funding can help your business move forward. Understanding what lenders may look at can help you prepare before you apply.
Here's something many business owners don't realize:
Lenders aren't just looking at your credit score.
When reviewing a business funding application, lenders may consider several parts of your financial picture. Depending on the lender and product, that can include credit history, business revenue, cash flow, time in business, existing debt, collateral, the purpose of the funds, and your ability to repay.
Requirements can vary significantly from one lender or financing product to another. That's one reason understanding your overall business profile matters.
Here are 7 things lenders commonly look at before making a funding decision.
1. Your Personal and Business Credit
Credit history is one of the first things many lenders consider.
Depending on the financing product and lender, they may review your personal credit, business credit, or both. Credit information helps lenders understand how you've handled financial obligations in the past.
A less-than-perfect credit score doesn't necessarily mean you have no funding options. Different lenders have different credit requirements, and some financing products place greater emphasis on other areas of the business.
The important thing is to know where you stand before applying.
If there are errors on your credit reports, unresolved accounts, or other issues that could affect an application, identifying them beforehand can help you make more informed decisions.
2. Your Business Revenue and Cash Flow
Revenue tells a lender how much money your business brings in. Cash flow helps show whether the business can support its financial obligations.
Lenders may review bank activity, financial statements, revenue trends, and other information to understand how money moves through your business.
The goal isn't simply to determine whether your business makes money.
A lender also wants to understand whether the business has the financial capacity to handle additional payments while continuing to cover normal operating expenses.
Having clean, organized financial records can make the funding process much easier.
- Is my revenue relatively consistent?
- Are my deposits easy to document?
- Are my operating expenses under control?
- Can my business comfortably handle additional debt?
- Do I understand where my money is going each month?
3. How Long You've Been in Business
Time in business can matter.
A business with several years of operating history generally has more financial information for a lender to evaluate than a brand-new business.
That doesn't automatically mean newer businesses can't obtain funding.
It means the programs available may differ depending on your company's age, revenue, credit profile, industry, and overall financial picture.
The goal is to explore funding that fits the business you actually have—not force your business into the wrong financing product.
4. What You Plan to Do With the Money
One of the most important questions you should be prepared to answer is:
Lenders want to understand the purpose of the funding.
Are you:
- Purchasing equipment?
- Buying inventory?
- Expanding?
- Opening another location?
- Hiring employees?
- Managing seasonal cash flow?
- Refinancing existing business debt?
- Purchasing commercial real estate?
- Taking on a new contract or large project?
Having a specific purpose for the funds shows that you've thought through how the capital may support your business.
5. Your Ability to Repay
This is ultimately one of the biggest questions a lender needs answered:
A lender isn't simply looking at how much money you want.
They're evaluating the relationship between your business's financial performance, its current obligations, and the proposed financing.
That's why the amount you request should make sense for both your actual business need and your financial capacity.
How much do I actually need?
What will I use the funds for?
How could the funding help my business?
How will the payments fit into my cash flow?
6. Collateral and Other Assets
Depending on the financing product, a lender may consider collateral.
Collateral can include assets such as:
- Real estate
- Equipment
- Vehicles
- Inventory
- Other business assets
However, not every funding option requires collateral.
Don't automatically assume you need to own a building or have significant assets before exploring your options.
7. Your Overall Business Profile
This is where everything comes together.
Lenders may look at the big picture rather than relying on one number.
Credit + Revenue + Cash Flow + Time in Business + Industry + Existing Debt + Funding Purpose + Repayment Ability
That's why two businesses with identical credit scores can potentially receive very different funding decisions.
Your business is more than a credit score.
What Can You Do Before Applying?
One of the best things you can do is prepare before submitting an application.
Consider having the following information readily available:
- Business formation information
- Recent business bank statements
- Profit & loss statements
- Tax returns, when required
- Information about existing business debt
- Revenue information
- Details about how you intend to use the funds
- Personal financial information, when required
- Information about business assets
The exact documentation varies by lender and financing type, so don't assume every lender will ask for the same paperwork.
Funding Should Fit the Business—not the Other Way Around
There's no single funding product that's right for every business.
A restaurant expanding into a second location may have completely different needs than a trucking company purchasing equipment or a contractor needing working capital to take on a larger project.
The goal isn't simply to get approved.
The goal is to find a funding solution that makes sense for your business, your cash flow, and what you're trying to accomplish.
Before accepting an offer, make sure you understand the rate, payment, fees, term, total repayment amount, and any collateral or personal guarantees involved.
Ready to Explore Funding Options for Your Business?
Tell us a little about your business, how much funding you're looking for, and what you're trying to accomplish. We'll help you explore potential financing options that may fit your needs.
Explore Funding OptionsSubmitting an inquiry does not guarantee approval or funding. Financing options, terms, rates, fees, and eligibility are determined by the applicable lender and may vary based on the applicant and financing product.